

Despite a 4.3 trillion dollar firm’s funding of opposition research, our idea is out there and supported by new replicable scientific evidence.
A 13 trillion Dollar Market
and A Looming Climate Emergency
Between 2017 and 2019, before the release of climate risk data by First Street, before assessments of financial institutions’ climate risk exposure, Matt Kahn and I wrote a paper presenting evidence in favor of the climate securitization hypothesis: mortgages exposed to climate risk are securitized and guaranteed by the government-sponsored enterprises. This paper caught the attention of senior New York Times reporter Chris Flavelle who, over a month in 2019, analyzed the results and asked series of questions. Chris won the National Press Foundation’s Feddie Reporting Award. We released an extensive code archive that the public can use.
The newspaper article was published on September 30, 2019. In the first hour after the release of the article, the download count of the paper increased quickly to more than 20,000. The New York Times had 2 billion readers in 2022. 61% of the readers are Gen Z or Millenials, who care more about climate risks. The more climate-skeptic senior leadership was shocked by our grassroots research effort to highlight the importance of climate risks. Our idea flowed to the rest of the world. The NYT recently announced that it had passed the milestone of 2 million international subscribers.
Bloomberg published our op-ed, “When Climate Change Causes Mortgage Defaults”. Bloomberg topped 500,000 subscribers in 2023.
Five years later, the Federal Reserve of Richmond did its own calculation and confirmed that we were right: in 2023, 27.2% of Fannie and Freddie’s mortgages may be exposed to future flood risk.
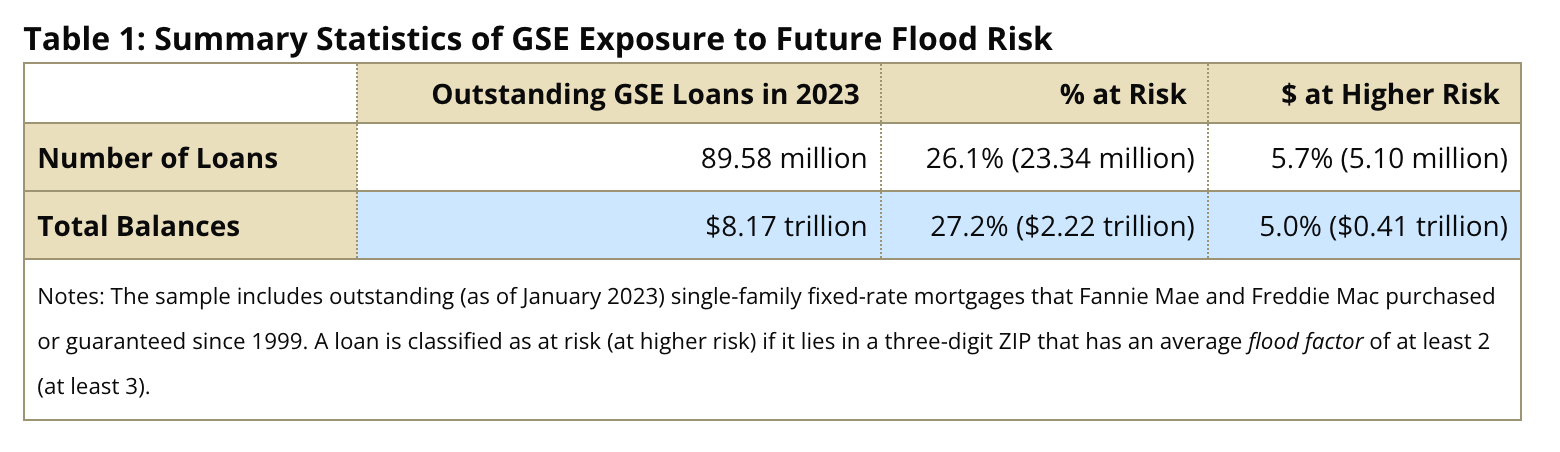
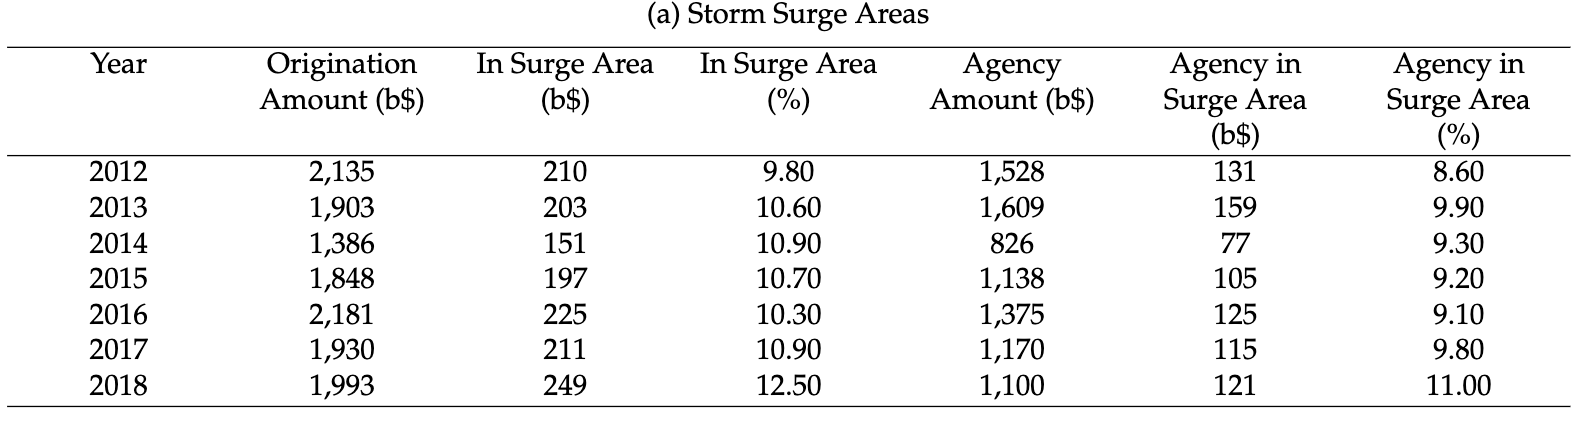
These 2023 numbers are even larger than my own estimates in 2019, suggesting that the agencies continue to hold large exposures to natural disaster risk.
Designing Strategies to Influence Research
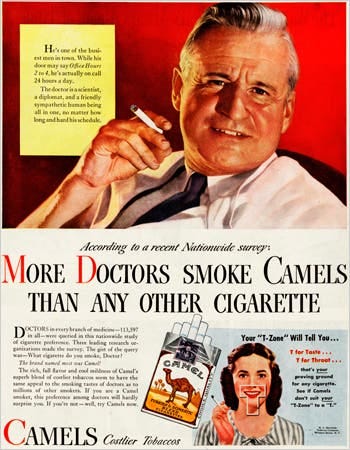
From the 1920s into the 1950s, doctors used to endorse Tobacco, with ads touting the benefits of, e.g. Camel cigarettes.
And as Allan M. Brandt suggests in his paper “A History of Tobacco Industry Tactics”:
Confronted by compelling peer-reviewed scientific evidence of the harms of smoking, the tobacco industry, beginning in the 1950s, used sophisticated public relations approaches to undermine and distort the emerging science.
The industry campaign worked to create a scientific controversy through a program that depended on the creation of industry–academic conflicts of interest. This strategy of producing scientific uncertainty undercut public health efforts and regulatory interventions designed to reduce the harms of smoking.
A number of industries have subsequently followed this approach to disrupting normative science. Claims of scientific uncertainty and lack of proof also lead to the assertion of individual responsibility for industrially produced health risks.
2024 is for climate risk and mortgage finance what the pivotal 1953 moment was for tobacco — when the link between cancer and smoking was well-established. High quality studies (see below) have established the causal impact of climate risk on mortgage performance, and have shown that such climate risk is transferred to the securitizers.
In 1953, taking control of the growing narrative linking cancer and tobacco consumption became essential:
Hill understood that simply denying emerging scientific facts would be a losing game. This would not only smack of self-interest but also ally the companies with ignorance in an age of technological and scientific hegemony. So he proposed seizing and controlling science rather than avoiding it. If science posed the principal—even terminal—threat to the industry, Hill advised that the companies should now associate themselves as great supporters of science. The companies, in his view, should embrace a sophisticated scientific discourse; they should demand more science, not less.
And that strategy has a clear playbook:
American Tobacco began to collect the public statements of scientists who had expressed skepticism about the research findings indicting tobacco. The company's own public relations counsel understood that it would be critical to create questions about the reliability of the new findings and to attack the notion that these studies constituted proof of the relationship of smoking to cancer.18
Pooling these efforts, Hill & Knowlton produced a compendium of statements by physicians and scientists who questioned the cigarette–lung cancer link. This compendium became a fundamental component of Hill & Knowlton's initial attempts to shape and implement its public relations strategy.
We can start to see the parallel between the actions of some firms on climate change research and those on tobacco.
Hill wrote in an internal memorandum. “There is no evidence that this adverse publicity is abating or will soon abate.” According to his media intelligence, at least 4 major periodicals (Look Magazine, Cosmopolitan, Woman's Home Companion, and Pageant) were planning articles on smoking and health.
In mortgage finance, the equivalent media storm is the set of articles published in the New York Times, (1, 2, 3), in Bloomberg (1, 2, 3), in Politico (1, 2), in the WSJ, in CBS News, on the securitization of climate risk. And it is particularly concerning because these climate-exposed mortgages are backed by goverment-sponsored enterprises, which in turn are explicitly backed by the US Treasury since 2008. This led to a hearing in Congress. And LLPA matrices went from obscurity to common knowledge.
Is this simply a large number of journalists duped by flimsy evidence?
Journalists at prestigious newspapers such as the New York Times, Bloomberg, the WSJ and Politico spend weeks researching a topic, interviewing multiple experts from a broad range of sectors. But let’s keep this argument aside, and let’s assume this large-scale-duping hypothesis is a possibility.
There was also an equivalent research storm, with papers showing that the financial sector transfers climate risk.
Bakkensen, L., Phan, T. and Wong, R., 2023. Leveraging the disagreement on climate change: Theory and evidence. Revise and Resubmit at the Journal of Political Economy. See Section 6.2 and Table 6.
Sastry, Parinitha. "Who bears flood risk? Evidence from mortgage markets in Florida." Evidence from Mortgage Markets in Florida (December 18, 2022). See Figure 3.
Nguyen, D.D., Ongena, S., Qi, S. and Sila, V., 2022. Climate change risk and the cost of mortgage credit. Published in the Review of Finance, 26(6), pp.1509-1549. See Section 6.1 Panel A.
Sastry, Pari, Ishita Sen, and Ana-Maria Tenekedjieva. "When Insurers Exit: Climate Losses, Fragile Insurers, and Mortgage Markets." Harvard Business School Working Paper, No. 24-051, February 2024.
(Updated May 2025: Baranyai, E. (2025) 'Do mortgage lenders offload climate-exposed loans to government-sponsored enterprises?', Finance Research Letters, 107749. Available online 7 June 2025. doi: 10.1016/j.frl.2025.107749.)
And finally, a policy storm, with reports by the President, the Commodity Futures Trading Commission (CFTC) on Managing Climate Risk in the Financial System, the Congressional Budget Office (CBO), and many others.
In short, a tsunami of evidence of the impacts of climate change on the securization of mortgages reached the desk of influential financial firms. What is an appropriate response? Something needs to be done.
Deploying Resources to Fight Climate Change Research
It is in this context that a 4.3-trillion-dollar firm deployed the familiar playbook described by Allan M. Brandt. This was also the playbook deployed during the 2008 financial crisis, tactics that the former FHFA head Mark Calabria denounced in his book “Shelter from the Storm.”
Let’s recap Allan Brandt’s points:
Associate yourself as a great supporter of science.
Embrace a sophisticated scientific discourse.
Demand more science, not less.
Produce a compendium of statements questioning the causal links.
The “compendium” here consists of a single comment, questioning the evidence of the transmission of climate risk into Mortgage-Backed Securities. This comment, explicitly funded by the firm with 4.3 trillion dollars of assets and by a group of firms interested in the results, provides evidence at odds with at least 4 papers, 3 reports, a Congressional hearing, and more than 10 media articles. That would seem to be a lonely fight.
Yet, it is possible to get temporary wins despite a consensus.
How does the research budget of a firm compares to that of an individual researcher?
The National Science Foundation reveals that the net income of this firm is of the order of magnitude of the entire non-federal funding for basic research. While academic journals require the disclosure of the existence of a funding, they can allow a privately-employed researcher with an affiliation to an academic institution to only disclose this academic affiliation — not the primary employment with the private firm.
Rules also do not mandate the disclosure of funding amounts. A $10,000 grant is very different from a $1,000,000 grant. The former funds one short conference travel, a little bit of research assistance, and perhaps a very minor data acquisition. The latter funds a research team and enables the payment of salary supplements. And we will never know whether it is $10,000 or $1,000,000. Or perhaps more. We could still be exposed to much higher opposition spending. Who knows.
Back to the playbook.
In the aftermath of the Congressional Hearings surrounding our work, policy circles and government-backed firms responded very differently. Some in Congress, in the offices of Sherrod Brown, Chuy Garcia, Pat Toomey, Sheldon Whitehouse, (notice both D and R here) wanted to have an open conversation. Some, like the FHFA’s Justin Contat and Will Larson (now at OFR) formed a taskforce to write a report. Freddie Mac invited us multiple times to discuss the evidence. FHFA organized a wonderful Econ Summit on climate risks. An open dialogue. It would be good to use modern econometric tools to investigate the heterogeneity of treatment effects.
Others stonewalled us, in a way familiar to the experience of the GFC (excerpts from Shelter from the Storm). And led an offensive that is akin, in its methods, to that led against these famous papers:
Mian, A., Sufi, A. and Trebbi, F., 2010. The political economy of the US mortgage default crisis. American Economic Review, 100(5), pp.1967-1998.
and
Keys, B.J., Seru, A. and Vig, V., 2012. Lender screening and the role of securitization: Evidence from prime and subprime mortgage markets. The Review of Financial Studies, 25(7), pp.2071-2108.
Both papers have been attacked and criticized, arguing that the Keys, Seru, and Vig misinterpreted the role of cutoffs. Or that the Mian and Sufi paper miscalculated the correlation between credit supply and income. Yet these papers became part of the history of economic thinking with series of replies. Arguably because the GFC was an abrupt event, and affected vast swathes of the financial sector, it was harder to attack than climate change, a slow moving disaster that is however sure to affect us in more profound and dramatic ways.
Academic work is not a palimpsest.
Or is it?
Back in 2018, before the start of the research.
We contacted a senior economist at Fannie Mae on Monday, January 22, 2018 to ask whether he’d be interested in research at the intersection of climate change and mortgage finance. In a brief phone call, we received a firm “no.”
We moved forward and self-funded research in the spirit of scientific inquiry, developing new techniques for economists, such as the systematic calculation of the footprint of multiple hurricanes (not just Sandy) with a classifier using USGS DEMs, the National Land Cover Database, hurricane wind cones, and HUD inspection reports.
This analysis is unique: there is still no paper estimating the footprint of 15 hurricanes at this scale. The main initial codebase, freely available, has 95,656 lines. The revisions have 20,278 lines, our first reply has 5,404 lines, and the final GitHub repo has 12,690 lines. This is a paper that had to design a number of new tools.
This paper is a Quest for Knowledge, a bridge towards a new research agenda (see ECTA paper).
Meetings with Matt Kahn were fun, interesting, and we felt that we were building something new. We know now that younger researchers built on our code in their work — they told us during coffees at the meetings of the American Economic Association, at the Urban Economics Association, or at AREUEA. The young generation wants to study climate risks. They know it will be the major story of their life.
Jeanne Sorin of the University of Chicago helped us study Hurricane Sandy — she’s an amazing researcher — and then, slowly, after months of careful inquiry, we expanded the data to cover 15 billion dollar events. At no point did we realize that we were about to create a policy storm. It was interesting and important to build a large and new code archive.
The “no” to collaboration led to immense pressure inside the agencies when the research was released: people were caught off-guard. There had not been a systematic collaboration between experts at NOAA, USGS, and financial experts at FHFA, Fannie Mae, Freddie Mac.
The issue had been taboo, in part because adverse selection in securitization is a topic that is not often discussed, which is intriguing given that both GSEs have combined balance sheets of 7.6 trillion dollars, and that the GSE securitization market is a 9.3 trillion dollar market. It’s been documented that conforming loans have higher Debt-to-Income ratios, higher LTVs, lower FICO scores.

We shared our data and code.
We outlined a research agenda that was policy forward.
We submitted a series of answers in response to a Request for Input. We suggested improving the data gap — the publicly available data we had access to could have had better geographic granularity. We thought that government sponsored firms would open up a bit to address this question.
In contrast, work by our firm-funded researchers did not add data points.
Some of our suggestions were about providing incentives for climate change adaptation:
FHFA should consider using its regulatory tools to encourage information discovery here. If home buyers are increasingly aware of the “known unknowns” involved in emerging climate risks, then they will be less vulnerable to future scenarios that may occur. The FHFA should inquire whether the GSEs have a proper incentive to research the emerging climate risks and to nudge the bank lenders to share their risk assessments with the households bidding for the homes.
A little bit after Christmas 2022, Matt sends me an email noticing a session at the AEA with our names. After years taking part in the interview process for INSEAD and HEC in Chicago, San Francisco, San Diego, I had decided to take a break.
But the AEA was calling back! I booked a flight and landed in New Orleans a few days later. The session rebutting our work was on a chilly morning at 8am. We were not invited.
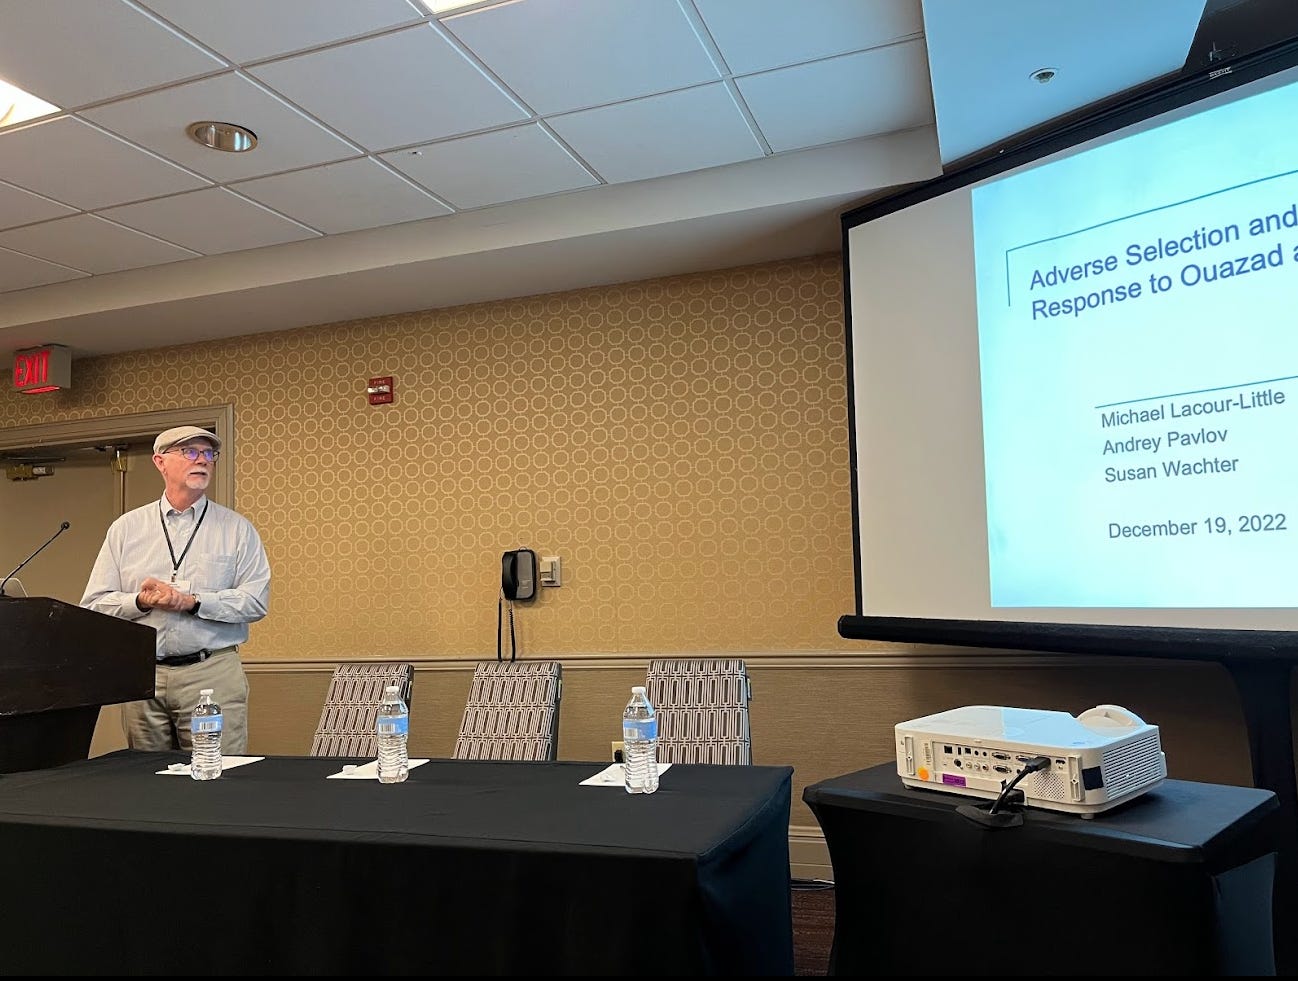
Nor was anyone in the audience allowed to speak. Brave young economists dared question the blanket ban on the pronouncement of a single word — and strongly suggested that we should be allowed to speak, even for 30 seconds. Young economists also questioned the findings at odds with most of the evidence of other papers. They had access to the data. While the affiliation of one of the authors is “the firm,” this affiliation is latter scrubbed in subsequent documents and replaced by an academic institution. Affiliations are also, probably, palimpsests. A much-needed appearance of independence.
Over the next few months, we discovered the opposition research was based on the data work written by a single MSc student.
The authors of this critique were surprisingly unwilling to share their data. We received a link a few months later from Andrei Pavlov. Download it. I invite everyone to download this archive — it won’t take you long to see that, seen within the expanding literature on difference-in-differences, there are major issues in the construction of the panel. The treatment years are often miscoded. This miscoding bunches at the conforming loan limit — and these are the absolutely essential observations. We document them line by line here.
Ouazad, A.C.L. and Kahn, M.E., 2023. Mortgage Securitization Dynamics in the Aftermath of Natural Disasters: A Reply. Available at SSRN 4445723.
Despite our serious scientific concerns, the Review of Financial Studies accepted the Fannie Mae-funded comment in a matter of a few weeks. An expeditious process that, as we will show next, did not spend much time inspecting the data archive.
We thought we had seen the code archive. But that was not the code posted on the Dataverse. The authors substituted another archive.
And because the public gets tired, the influence playbook works.
It took us a year to realize that an entirely new data archive had been posted. When we did, we analyzed it (open it too without our guidance or point of view) and we documented our findings here:
Kahn, M.E. and Ouazad, A.C.L., 2024. Ouazad and Kahn (2022) Replicates: A Detailed Analysis of LLPW (2024). Available at SSRN.
We discovered serious breaches of scientific methods such as manual data exclusions for a substantial number of ZIP codes exposed to hurricane storm surges, including Katrina and Sandy. The SSRN provides line numbers and file names.
The dataset manually excludes Ditech, again a problematic lender that failed.

We discovered a large failed outer join (a rookie mistake) leading to tens of thousands of missing data for a key variable (the high cost dummy). The code was written in Matlab, which most graduates know is not the right tool.
We made this analysis easily digestible here:
Our Evidence is Solid
We also wanted to be constructive. We produced a new, improved data archive on GitHub with a wide range of specifications.
You can download it at this link:
You can check for yourself and decide whether you trust us.
One of the fantastic outputs of this analysis is the set of point estimates obtained with a range of different specifications and fixed effects. We became proud of our spirit of scientific inquiry. When do results hold? I invite you to make up your own mind by looking at the evidence. Another output is the set of linear tests for the null hypothesis that the post-hurricane dummies are equal to zero.
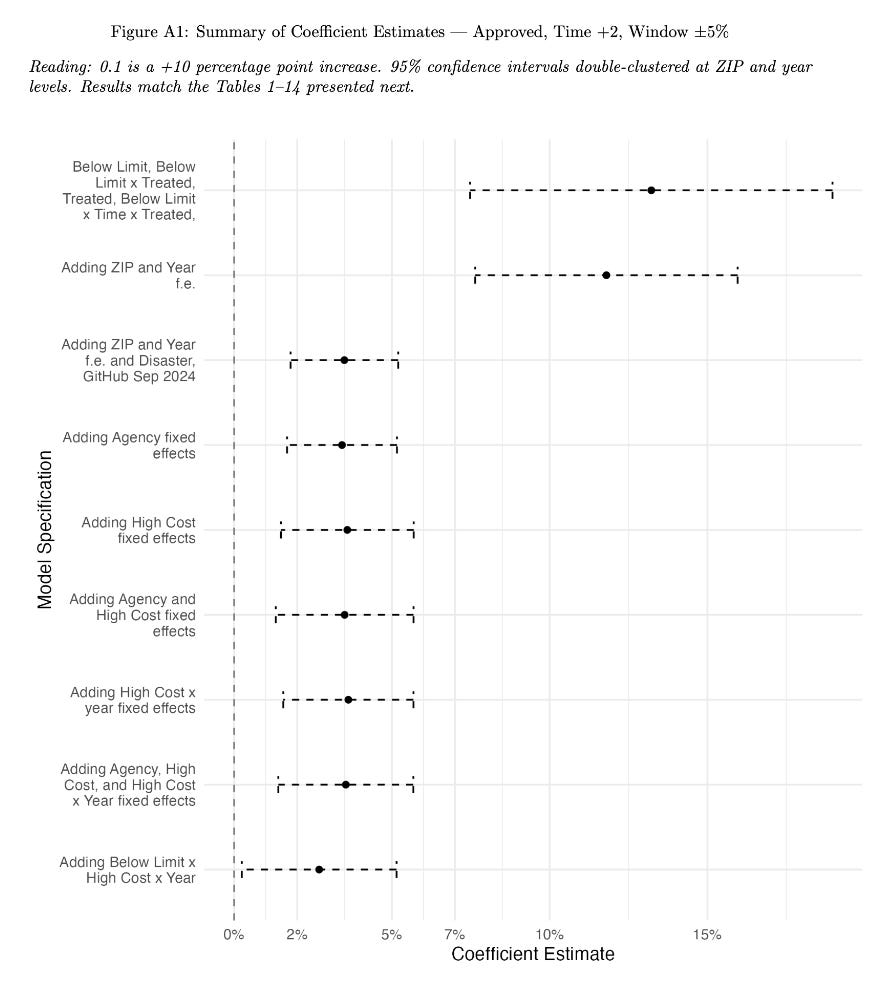
The authors kept mentioning the rounding of numbers: conforming loan limits should be rounded.
We thus used a “gold standard” to get a clear scientific answer to the question of loan amount rounding. McDash establishes jumbo status before rounding loan amounts (you can verify this by tabulating jumbo status by loan amount). We used this “IsJumbo” variable to establish which rounding method was the best: should we use our agnostic approach, or show we round numbers? We didn’t know what to expect. And we found, unambiguously, that not rounding limits performed much better in mitigating misclassfication. The misclassification of loans as Jumbo or conforming was significantly worse with their approach.
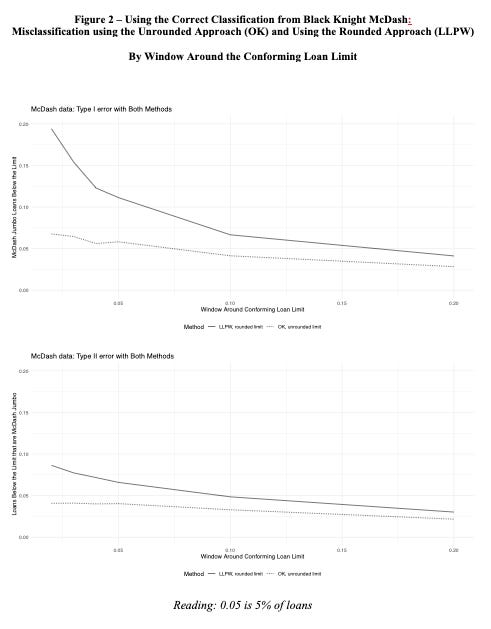
This is important because of the dramatic bunching of loans on the left side of the conforming loan limit. It also makes us wonder why the data supplied by the securitizers rounds loan amounts and does not provide a jumbo variable. This certainly makes it harder for us researchers to test any securitization hypothesis.
We also performed a literature review to see if there was a precedent in this discussion of rounding, and found one lonely unpublished pdf with a paragraph. Not exactly the industry standard that our opposition researchers claim.
We spoke to prior editors of RFS, editors of major econ journals, who read the documents. They found the current assessors’ approach uncommon — some expressed respect and admiration for the work, stating that was an important piece of research. Many suggested that a published reply was the right course of action. None of the robustness checks display negative coefficients. Many display statistically significant coefficients with substantial ecoomic magnitude.
We sent two letters to Tarun Ramadorai detailing the scientific findings and the replicable code.

Ultimately, this scientific work didn’t matter for the unobservable team of assessors. We also noticed downloads of the data and code from central DC and many other locations right even though they were shared in confidence only with one person.
The Firm’s Final Push
A new wave of news put more pressure. We did not initiate it.
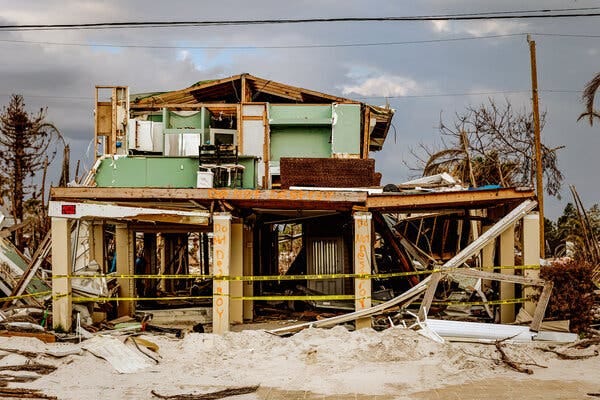
The New York Times’ Lydia DePillis wrote an article that cites us, titled:
Mortgage Regulators Are Shrugging Off Climate Risk. It Could Cost Taxpayers Billions.
Fannie Mae and Freddie Mac, which backstop most U.S. mortgages, know floods and fires are a growing problem. But little action has been taken.
And Bloomberg’s Eric Roston wrote:
A few days after the second piece, widely read, the pressure on the RFS team to retract our paper must have been extreme.
After months of silence, in the wake of Christmas day, we suddenly received the following email:
The editorial team are retracting this article because the original findings cannot be replicated when correcting these issues.
with no report attached.
Despite the rounding point having a clear scientific answer — we should not round conforming loan limits —, this point was accepted without explanation.
The firm-funded piece of research achieved a minor success despite the scientific evidence.
Academic journals provide readers with peer-reviewed work. Yet, deliberations increasingly happen behind closed doors.
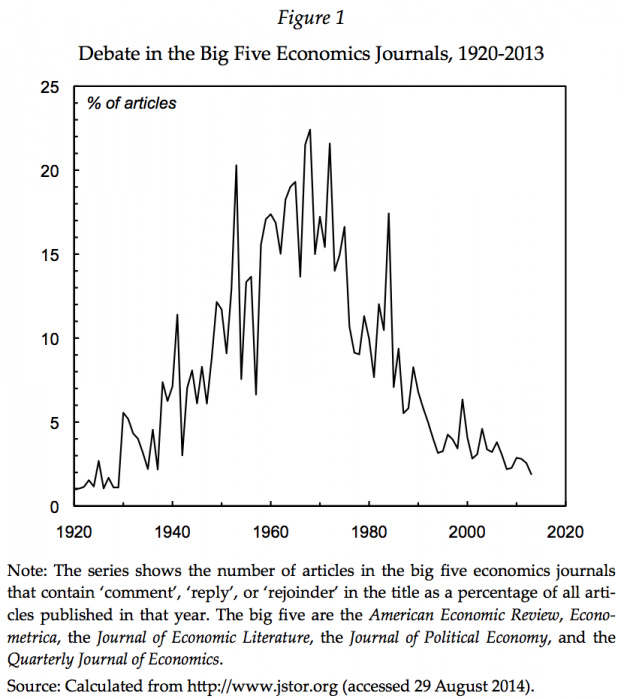
We requested information from the editor of the RFS: a report, an analysis, a disclosure of potential conflicts of interest; something more than one line.
These messages were left unanswered, except a statement from Tarun Ramadorai that there would be no disclosure of potential conflicts of interests of any member involved in the review.
This is leaving us — and the millions of readers of the New York Times, Bloomberg, the WSJ, Politico — asking whether this decision was the outcome of an independent process; and asking why a paper with a detailed set of documented mistakes can stand, despite COPE guidelines mandating retractions for data mistakes and conflicts of interests. Will Oxford University Press be comfortable with this choice? Open question.
How the Research Changed Everything:
A Fast-Expanding Research Agenda
There is a silver lining. The history of economic thought moves forward.
New research is written everyday on this topic and many have confirmed our findings.
A familiar chasm between leadership and staff described in Mark Calabria’s book seems to be at play here.
Can the genie be put back in the bottle? I doubt it.
We thought that this firm-funded comment would release new data. We thought it would open up new research agenda:
when do lenders securitize climate risk?
how should we structure mortgage backed securities and their tranches?
A research team at the New York Fed answers the ‘when’ question: Blickle, Perry and Santos (2024) finds evidence that non-banks and local banks are more likely to securitize/sell mortgages to borrowers prone to flood risk.
The “how” question is addressed in our new paper.
Kahn, M.E., Ouazad, A. and Yönder, E., 2024. Adaptation using financial markets: Climate risk diversification through securitization (No. w32244). National Bureau of Economic Research
which FHFA and Freddie Mac welcomed, but not Fannie Mae. We remain confident that these are useful tools to address the issues we raised in our first work. The paper has received more than 10,000 views as of now.
This fascinating conversation — can we adapt? — wasn’t opened by the comment. The comment relies purely on public HMDA and does not offer a big picture analysis.
Instead, we can reread Allan Brandt’s description of opposition research:
The very nature of controlling and managing information in public relations stood in marked contrast to the scientific notion of unfettered new knowledge. Hill and his clients had no interest in answering a scientific question.
The Scientific Community Crowdsources Truth
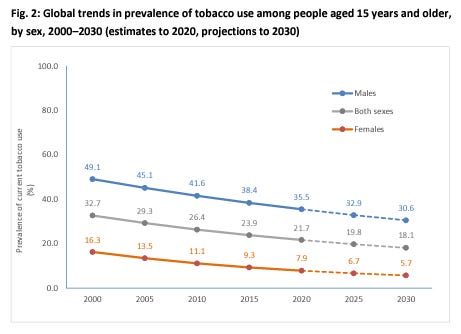
Are we all doomed to fall prey to private interests funding flawed research? The experience of tobacco suggests that it delays progress but does not ultimately stop it. Tobacco consumption is strongly declining according to the World Health Organization, “despite tobacco industry efforts to jeopardize progress.”
And the academic world does form its own collective thinking on each topic. There is a Conflict-of-Interest Discount in the Marketplace of Ideas quantified by John Manuel Barrios of Yale, Filippo Lancieri of Georgetown University, Joshua Levy of USC, Shashank Singh of the University of Chicago, Tommaso M. Valletti of Imperial College, and Luigi Zingales of the University of Chicago.
Here is the second part of the abstract:
On average, a conflict of interest decreases trust in the conclusions of an economics paper by 30%. This reduction in trust reflects a combination of the frequency of conflicted papers and the bias of papers when they are conflicted. To isolate the second term, we introduce a key construct: the CoI Discount, which measures the reduction in the value of a conflicted paper relative to a nonconflicted one. We show that, on average, conflicted papers are worth less than half of non-conflicted ones, though this effect varies significantly depending on the nature of the conflict. The discount is more pronounced when the conflict involves the interest of a private rather than a public entity.
The scientific community crowdsourced truth, with, as of now, 246 citations for our work compared to the 9 citations that the opposition piece has garnered. Have some of the 246 citations been routine copy-and-paste citations?
A majority of citations, especially from policy circles in DC and from the Federal Reserve System, come from authors well-acquainted with the data sources and the institutional mechanisms.
Sources told me that, in 2020, FHFA conducted an extensive internal analysis of the internal data and concluded that, yes, they were able to find these effects with more granular data than the publicly available HMDA.
And a DC-based senior federal staff told me candidly that “I won’t say it publicly, but I owe you my job.”
Happy to help.
Our research agenda moves forward.
A Wave of Negative Climate Policy News
As I’m writing this:
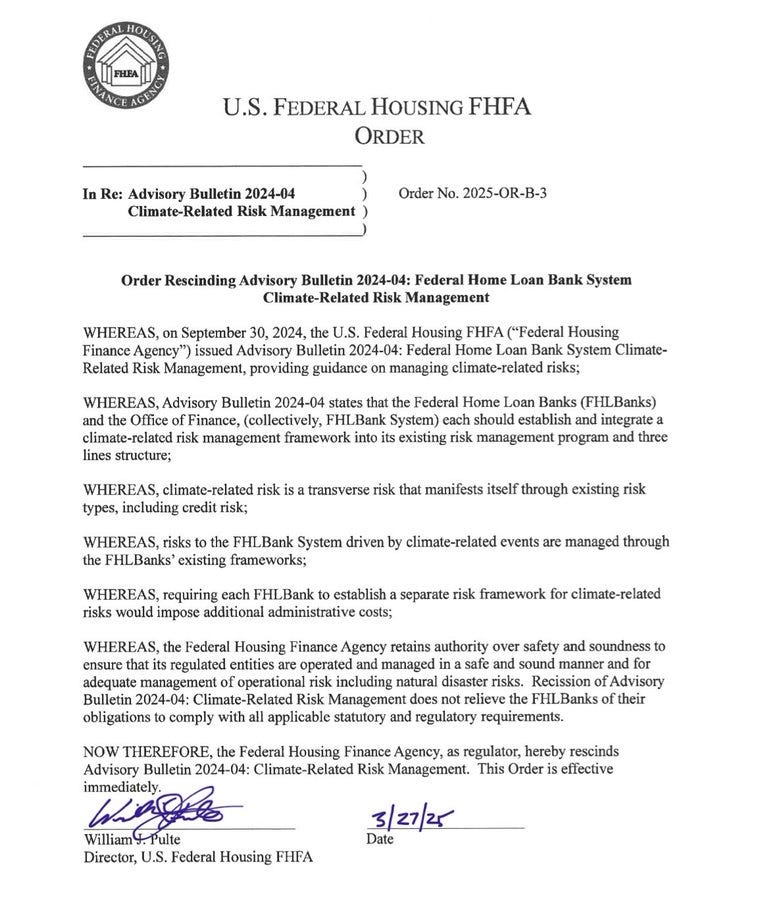
On Jan. 17, 2025, The Federal Reserve Board withdrew from the Network for Greening the Financial System, jeopardizing the work of many bright climate economists in the Federal Reserve System.
On Jan. 20, 2025, The new Trump administration withdraws the US from the Paris agreement.
On Jan 23, 2025, our retraction notice was officially published.
On Feb 3, 2025, Most CFPB work is frozen by its new head. The Consumer Financial Protection Bureau hosts Home Mortgage Disclosure Act data, at the core of our empirical work.
On Feb. 5, 2025, NOAA employees are told to pause work with foreign nationals. NOAA provides hurricane data throughs its National Hurricane Center. Again, NOAA data is at the core of the definition of our treatment group.
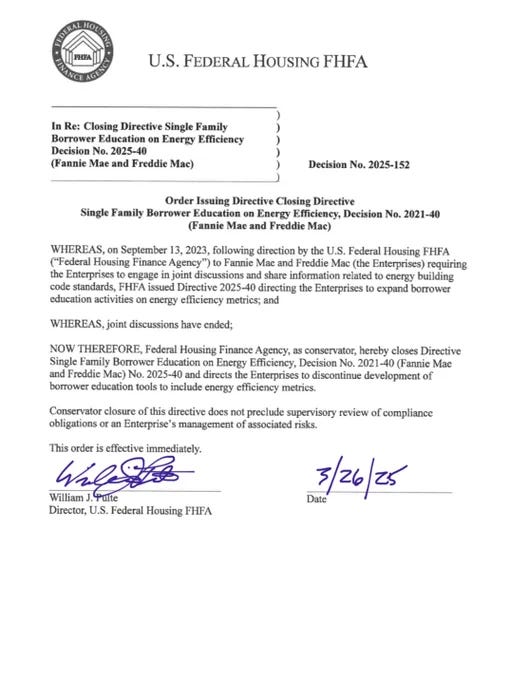
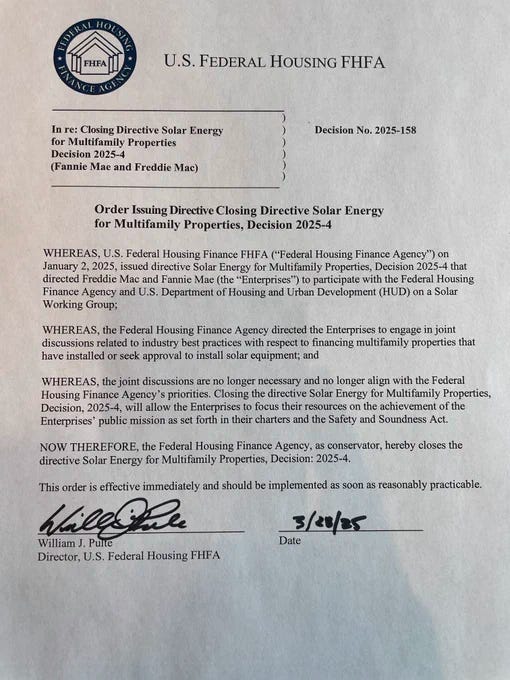
We will have to see what happens at FHFA.
Update:
How Fast Does Paul Revere Ride?
I am worried about delaying the process of climate change adaptation not only in the United States, but in Canada and throughout the world. For better or for worse, the US has been setting the example for the whole world, but that will likely change now as Canada’s conversation decouples from the US.
If all of us in this field are the Paul Reveres of climate change adaptation, does a message travel at the speed of sound, or at the speed of snail mail?
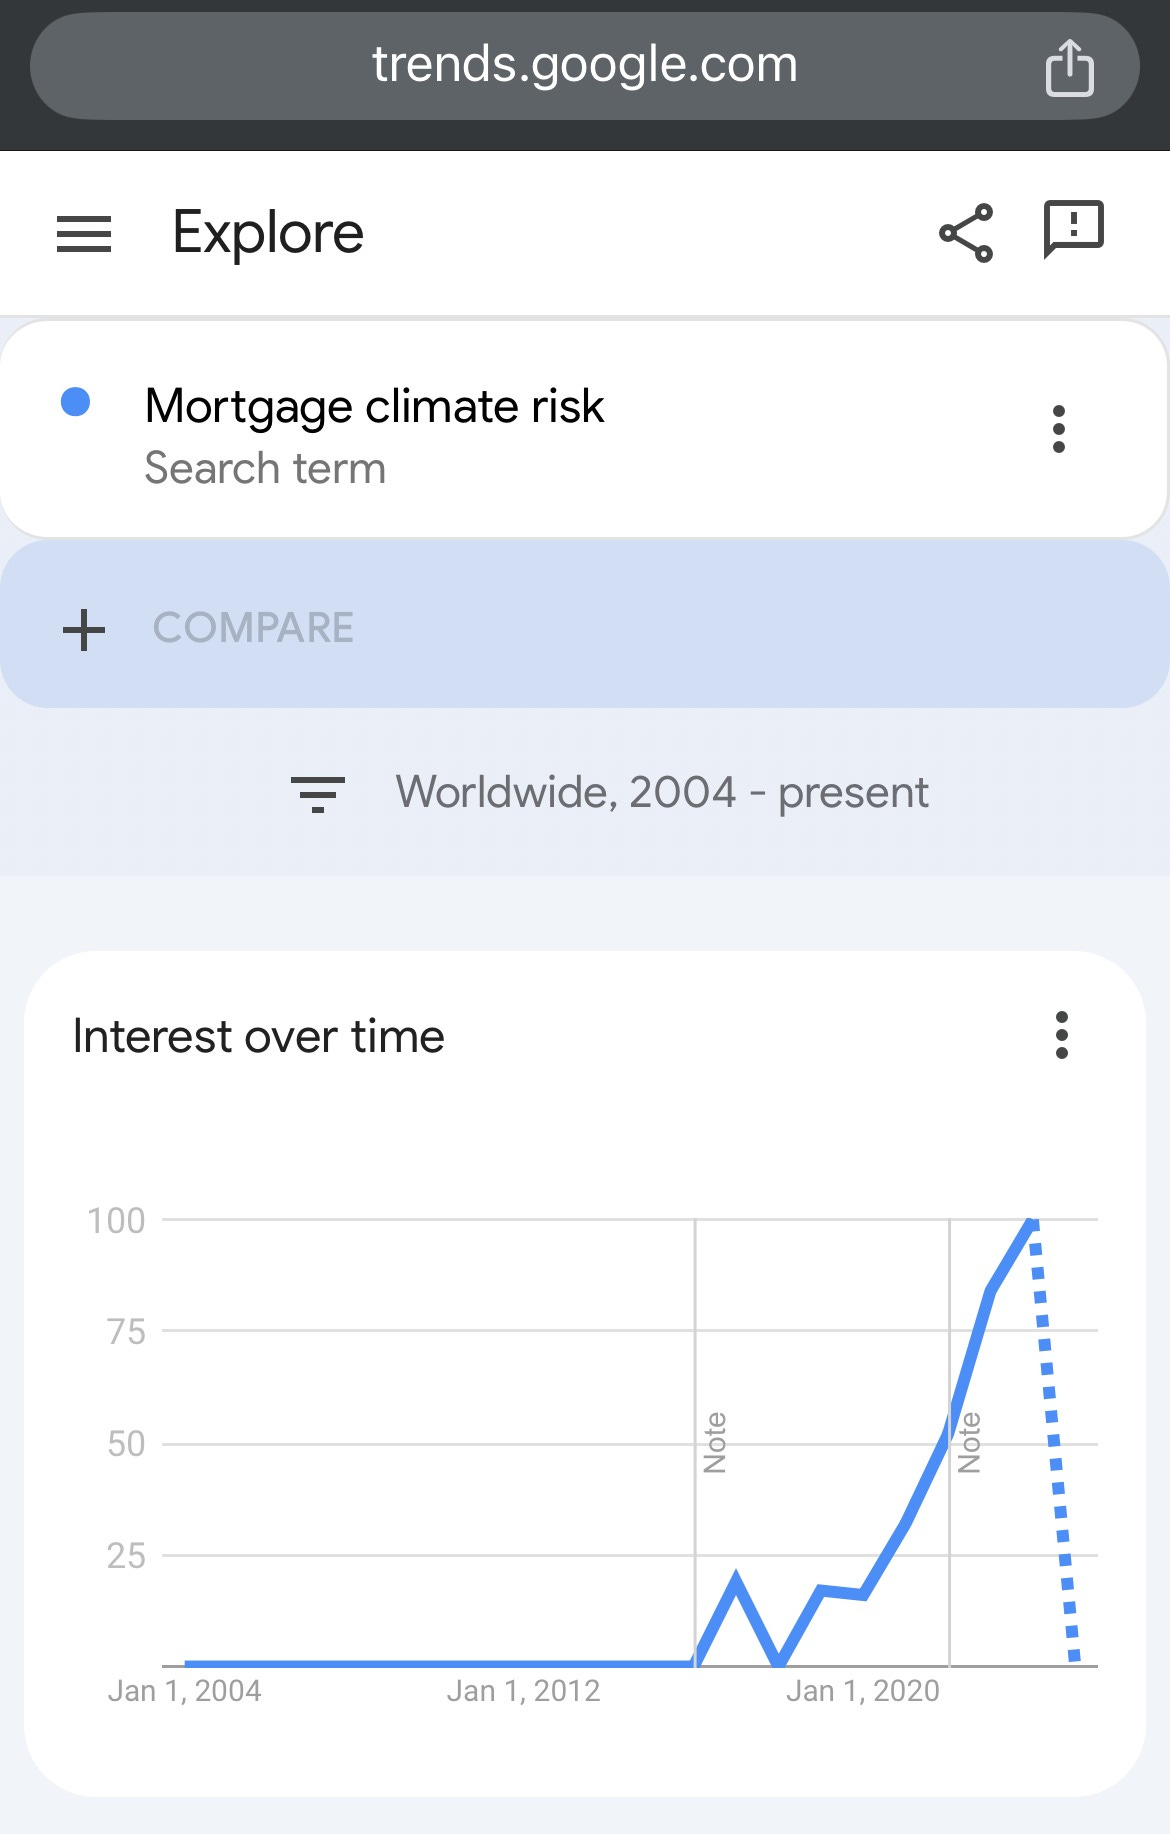
Our paper coincided with a very significant uptick in interest in mortgage finance and climate risk. This is the Google Trends report. Our paper was issued at the end of 2019.
Yet, progress in reaching the goals of the Paris Climate agreements is slow and we are not making progress at the pace needed to reach its goals. We might already have crossed the 1.5 degree Celsius increase. Wildfire frequency and their impacts are rising fast. And the science of climate change adaptation leaves me puzzled, with papers showing convincing evidence of adaptation, and others showing rising impacts. We need a nuanced take on this, and we need to avoid the self-censoring of research when it discusses the securitization of climate-risk exposed assets.
We believe in transparency and constructive research. We are working on providing constructive tools to adapt to climate risks. We are building tools to understand the role of flood protection infrastructure for real estate.
Ouazad, Amine Charles-Louis and Kahn, Matthew E., Time Consistent Infrastructure Investments: Optimal Flood Protection Policies in Spatial Equilibrium (December 26, 2024).
We are confident that our work continues to change the course of scientific debate. When I watch the numerous high quality sessions on climate risk in conferences, I know we have made a mark.
As a professor of one of the UCs once told me “You should be proud.”
And so we will be releasing new work on the securitization of climate risk in 2025. How have both the industry and the nature of disasters changed since our work? Data will tell.